A Case Study in Payment Settlement Drift
By Oladipupo Akin-Tepede
Senior Business Analyst & Lean Six Sigma Black Belt
Nigeria runs one of the most sophisticated high-frequency instant payment ecosystems in the developing world.
In 2024 alone, the Nigeria Inter-Bank Settlement System processed over ₦1.07 quadrillion across 11.3 billion transactions.
To handle that volume, banks and fintechs lean heavily on automated AI engines for real-time fraud detection, credit scoring, and transaction routing.
On paper, these risk engines perform well. In standard off-peak testing, they hit 98% accuracy at distinguishing legitimate transactions from fraud.
Yet every payday, every major holiday, every sudden shift in central banking directives, the same systems degrade. Millions of legitimate POS and mobile transfer attempts get flagged as suspicious, stuck in pending states, or declined outright.
The Cause: Payment Spikes as Out-of-Distribution Data
A fraud or routing model trained on normal, off-peak transaction behavior learns under predictable traffic assumptions. Peak Nigerian commerce windows break those assumptions. Take a Friday evening POS run across Lagos:
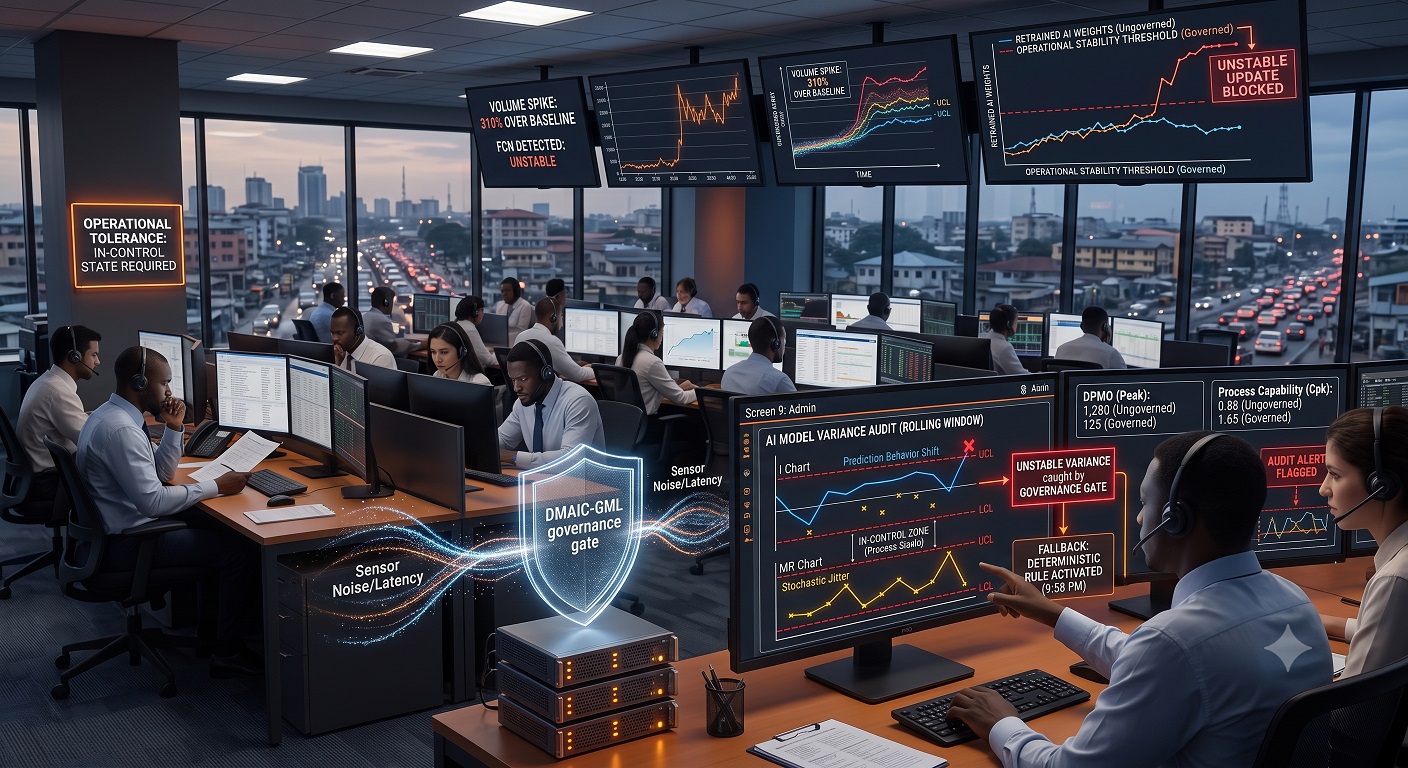
Transaction volume can spike 300% within minutes
Inter-bank switching delays create timestamp mismatches between originating and receiving institutions
Consumers suddenly shift from mobile apps to USSD or POS terminals, distorting the model’s usual input patterns
In machine learning terms, this is textbook out-of-distribution drift.
An ungoverned model facing that noise does what any uncertain system does. It plays it safe, over-indexing on risk. The result is a surge in false positives: legitimate transfers fail, merchant POS terminals freeze, and customer service queues fill with chargeback complaints.
The Governance Fix
Patching this doesn’t mean building a bigger model. It means governing model variance in real time.
When an automated transaction engine retrains on incoming system logs, the updated weights or thresholds shouldn’t go live automatically. They need to pass through a statistical checkpoint first, one that audits how much the model’s prediction behavior has actually shifted across a rolling window of recent transactions, rather than trusting a single static accuracy score.
If sudden latency or load spikes push that variance past a defined stability threshold, the governance layer catches it before customers do:
The system falls back to a safe, deterministic decision rule
The unstable update gets blocked
An audit alert is flagged
All before thousands of legitimate transactions get wrongly blocked.
The Enterprise Takeaway
In high-frequency financial infrastructure, a smart AI model with no process control is a liability, not an asset.
Apply Lean Six Sigma governance to a real-time machine learning pipeline, and you eliminate prediction drift, protect customer trust during peak volume, and turn a non-deterministic algorithm into something an institution can actually depend on.
How is your institution managing model performance during extreme traffic and load shifts? Let’s discuss in the comments below.
